Commercial lending activity across Pennsylvania has stayed steady even as interest rates shift. Property owners who refinance often assume the process moves faster than a purchase did. A lender will still often want a current ALTA survey before final approval, even though the borrower already holds the deed.
Refinancing Creates a New Round of Property Due Diligence
A refinance is not just a new stamp on the same loan. When a property owner refinances, a new lender, or even the same lender offering new terms, often looks at the property again from scratch. That second look can include a fresh review of the title and the physical site. An ALTA survey often comes up during that review, even though the borrower has owned the property for years and nothing has changed hands.
This surprises some owners. They assume that because they already hold a clear title, no new survey should be needed. But the lender writing the new loan has its own underwriting rules. Those rules are set by the institution, the title insurer, and sometimes an outside investor buying the loan later. Each party may want confirmation of what the collateral looks like right now, not five or ten years ago.
The Building May Be the Same, but the Collateral Record May Not Be
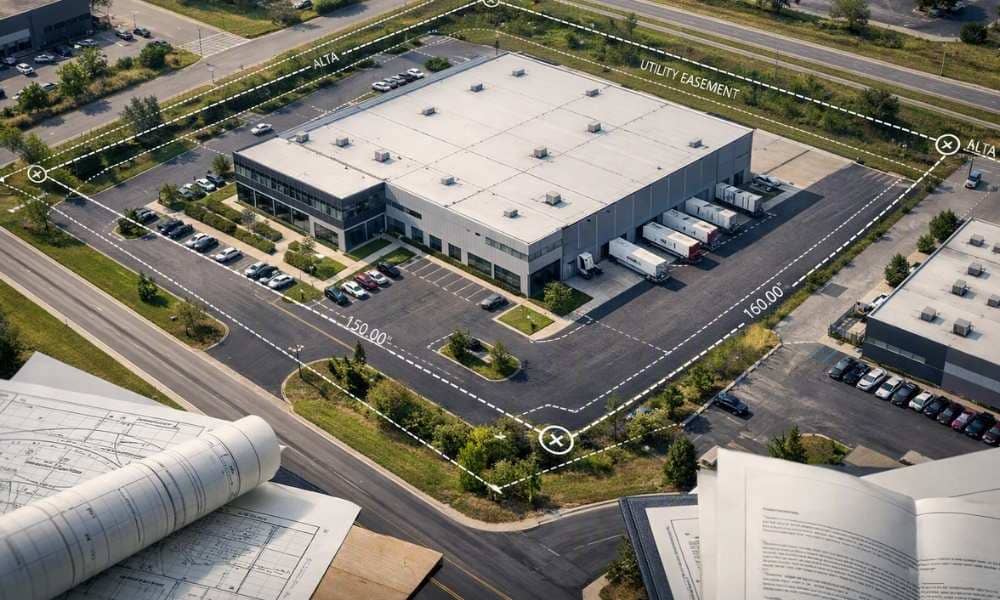
A lot can happen to a commercial property between its first loan and its refinance. An owner might add a loading dock, repave a parking lot, or open a new access point off a side street. Utility lines may have been rerouted since the last loan closed. A neighboring parcel might have been combined with the original lot, or a new easement might have been granted for a shared driveway or a stormwater line.
None of these changes show up on an old survey. A lender looking at the property today has no way to know about them unless someone points them out or a new survey captures them. That is one reason a lender may want current site information rather than relying on the file from the original loan closing. A moved fence line or a drainage easement recorded last year can matter to a lender’s decision.
Why an Old ALTA Survey Does Not Automatically Satisfy a New Lender
An older ALTA survey is not automatically invalid. Surveys do not carry an expiration date printed on them. But whether an existing survey works for a refinance depends on several things: the lender’s own requirements, the title insurer’s position, how old the survey is, and whether the property has changed since it was drawn.
Some lenders will accept a survey that is a few years old if nothing has changed and the title insurer agrees to rely on it. Others want a survey completed within a set window before closing, often within the last six months or year. A title insurer may also ask for updated certification language before it will issue a policy based on an older drawing. Each transaction sets its own rule, so it helps to ask early rather than assume the old survey will pass.
Refinancing Can Change Who Needs to Be Named on the Survey
An ALTA survey includes a certification statement. That statement lists who the surveyor is certifying the work to, usually the owner, the lender, and the title company involved in the transaction. When a property refinances, the parties named on the old survey are often not the same parties involved in the new loan.
A survey certified to a lender from years ago cannot simply be handed to a new lender and expected to work. The new lender’s name, the current title company, and any other party relying on the survey need to be named directly. A surveyor should get the current transaction instructions before starting the work, rather than copying certification language from an older file. The ALTA/NSPS standards keep survey information consistent across lenders and title companies, but the certification itself still has to match the people involved in this loan.
Order the ALTA Survey Before the Refinance Reaches Its Final Review
Not every commercial refinance calls for a new ALTA survey. Requirements vary by lender, title insurer, and loan program. Some smaller loans or portfolio refinances may not need one at all. The best first step is asking the lender or the title company directly whether a survey is required, and if so, what scope they expect.
Once that is clear, the surveyor needs the current title commitment and a list of what the transaction requires. Table A items are optional additions beyond the base ALTA survey, things like flood zone data, zoning classification, or utility locations. Deciding which of those apply early on saves time later in the loan timeline. Field work, drafting, and any revisions the title company or lender requests all take time, so starting this step well before the closing date gives everyone room to review the results and ask questions.
Frequently Asked Questions
Does every commercial refinance require a new ALTA survey?
No. Requirements vary by lender, title insurer, and the details of the transaction. Some lenders will accept existing survey information if nothing about the property has changed. Others will request a new or updated ALTA survey as part of their underwriting. The best way to know for certain is to ask the lender directly during the early stages of the loan.
Can the ALTA survey from the property’s original purchase be reused for refinancing?
Possibly, but it should not be assumed without checking first. Its acceptability depends on how old it is, whether the property has changed since it was completed, and what the current title information shows. The lender and title insurer involved in the new loan also have their own requirements to consider. Confirming this early avoids delays later on.
Why would a lender request an ALTA survey when the borrower already owns the property?
Because refinancing still means the lender is evaluating the real estate that will secure the new loan. The property serves as collateral whether it is a purchase or a refinance. A lender may want current survey information to review alongside today’s title work and loan terms. Ownership staying the same does not mean the collateral has stayed the same.
Should a property owner order an ALTA survey before receiving the lender’s survey instructions?
It is usually better to wait until the required scope is confirmed first. That helps the surveyor understand who needs to be named, what title documents apply, and whether any optional items are requested. Ordering a survey too early can mean redoing parts of it later. A short conversation with the lender or title company up front can save time.
Can renovations completed after the previous loan affect a refinance survey?
Yes. Physical changes made since an earlier survey, like a new addition, a moved fence line, or an added parking area, can make that older survey less accurate for today’s property. Whether the lender needs a full new survey or just an update depends on the transaction and how much has changed. Pointing out known changes to the surveyor ahead of time helps the work move faster.